MongoDB is back in focus after BTIG began covering the company with a positive view that leans on its subscription database platform and expectations for revenue growth above 20% over the next few years.
The backdrop is a much larger MongoDB than at its 2021 peak, with revenues now 257.6% higher and operating losses nearly closed. This makes any fresh analyst attention more about business scale and profitability progress than short term market moves.
We will now look at how MongoDB’s evolving revenue profile and BTIG’s growth-focused coverage could influence the broader investment narrative.
Scan beyond MongoDB and spot other fast-growing software plays that pass fundamental checks with our curated list of 20 high quality undiscovered gems.
Advertisement
MongoDB Investment Narrative Recap
To own MongoDB, you need to be comfortable with a story built around data growth, Atlas cloud adoption and the AI features outlined in the analyst consensus Narrative on Simply Wall St. That view leans on ongoing revenue expansion of about 16% a year and earnings growth above 20% while the business keeps tightening its cost base.
The next short term swing factor is the Q3 FY27 result on 1 December 2026. Investors will want to see Atlas and AI usage translating into revenue and margin progress. Competitive pressure from cloud provider databases and leadership turnover remain the biggest operational risks if they start to slow customer uptake.
The most relevant fresh development is BTIG’s new coverage of MongoDB, paired with its expectation for revenue growth above 20% over the next few years. That sits slightly above the 16% annual revenue growth that analysts in the Simply Wall St dataset currently forecast, so it brings attention to whether recent execution can support faster expansion.
For you, the practical link is timing and proof points. The upcoming Q3 FY27 earnings release is where management can either support BTIG’s more upbeat growth view through Atlas, AI and enterprise contract metrics, or leave the analyst consensus Narrative on Simply Wall St intact if trends align more closely with existing 3 year forecasts.
MongoDB’s narrative projects US$4.8b revenue and US$270.0 million earnings by 2029. This projection assumes 19.6% yearly revenue growth and an earnings increase of about US$211.1 million from US$58.9 million today.
Discover why MongoDB’s fair value indicates a 35% potential upside to its current price. This gap could narrow quickly.
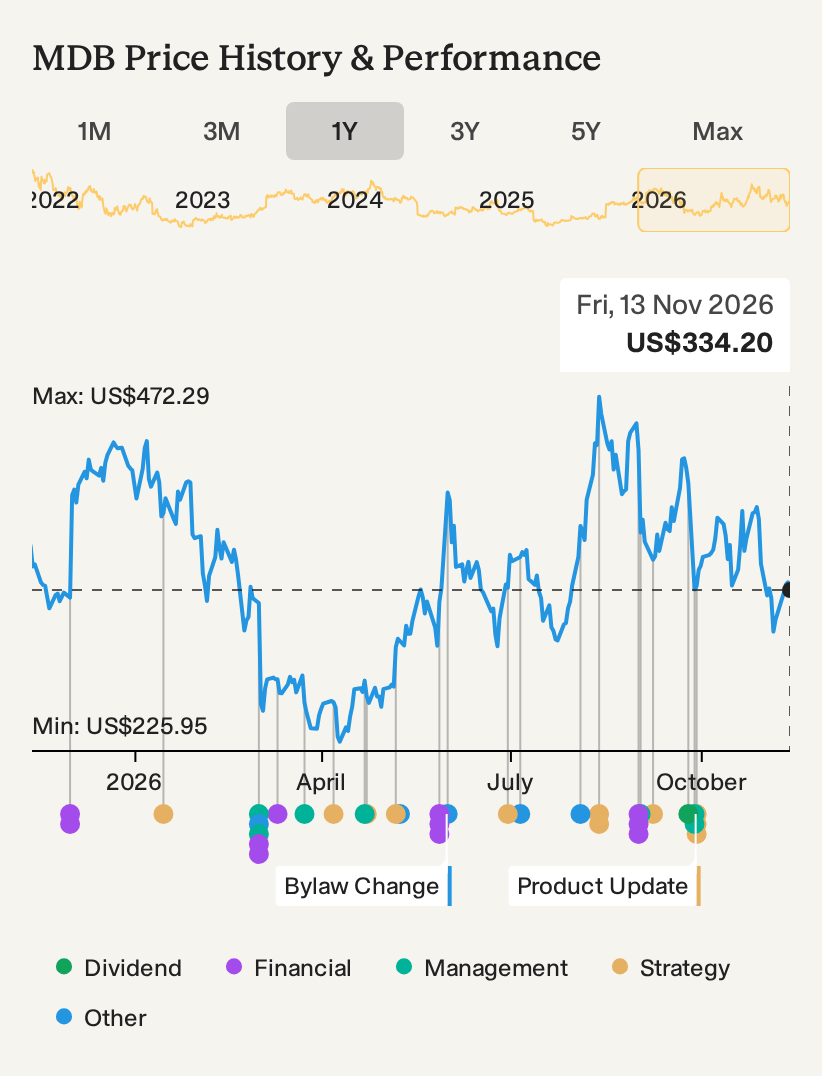
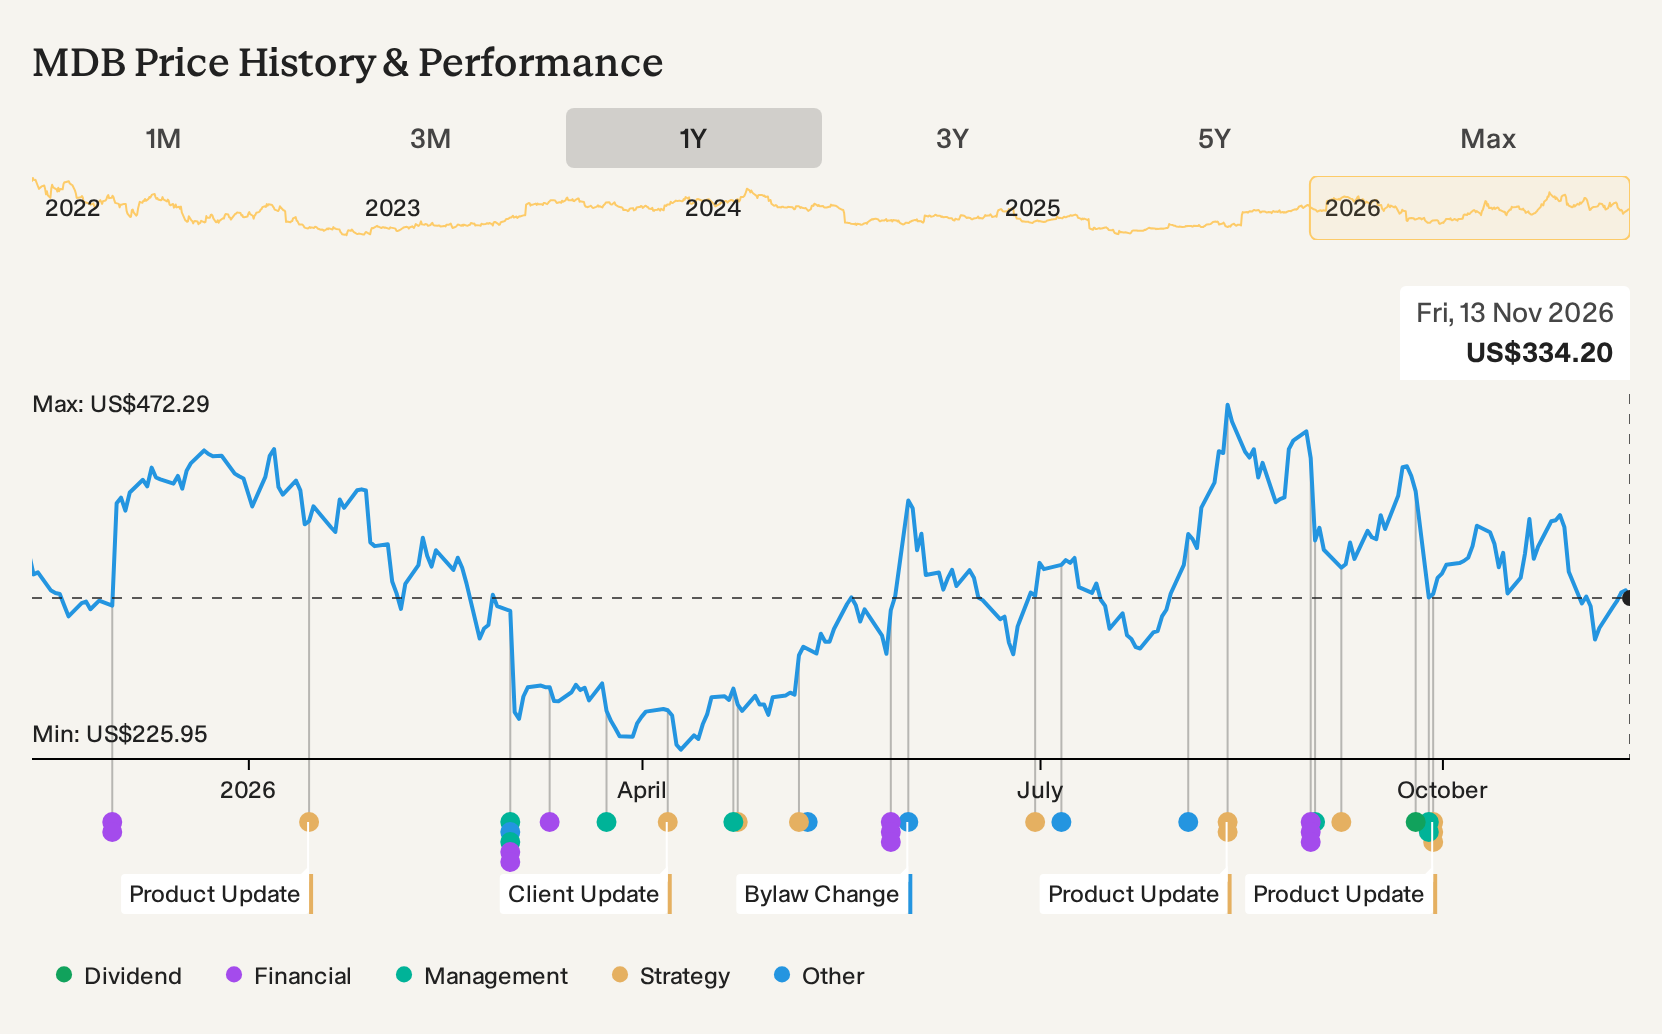
NasdaqGM:MDB 1-Year Stock Price Chart
Exploring Other Perspectives
One alternate view puts the legal overhang front and center for MongoDB. The most cautious analysts were penciling in roughly US$4.5b of revenue and only about US$39.0 million of earnings by 2029, which is far below consensus. That creates a sharply more pessimistic story that BTIG’s fresh coverage could eventually challenge or reinforce.
Don’t just follow the ticker; dig into the data and build a conviction that’s truly your own.
Looking for more MongoDB style investment ideas?
If you want to apply the same kind of disciplined, fundamentals first approach used to assess MongoDB, the Simply Wall St Screener can help you surface other companies that match your preferred balance of growth, quality and risk.
Valuation is complex, but we’re here to simplify it.
Discover if MongoDB might be undervalued or overvalued with our detailed analysis, featuring fair value estimates, potential risks, dividends, insider trades, and its financial condition.